
















Why can a US stock market leader surge 20% in a single day on strong earnings, while a hot A-share stock hits its daily limit-up with buying demand drying up? Why has the US market delivered a decade-long bull run, while A-shares are known for sharp rallies followed by steep sell-offs?
The fundamental difference lies not in corporate quality, but in two entirely different underlying operating mechanisms. Coinmeta's US Stocks section focuses on the characteristics of US stock movements, examining five core dimensions—price limits, circuit breakers, trading rules, short-selling ecosystem, and investor structure—to help you understand the distinct rules of these two very different markets.
Comparison Table: US Stocks vs A-Shares Price Movement Characteristics
| Comparison Dimension | US Stock Market | A-Share Market |
|---|---|---|
| Price Limits | No individual stock price limits | Daily price caps in place |
| Circuit Breaker Mechanism | Index-level circuit breakers | Non-market-wide circuit breakers |
| Trading Rules | T+0 settlement | T+1 settlement |
| Short-Selling Mechanism | Mature short-selling, two-way pricing | Restricted short-selling, limited eligible stocks |
| Investor Structure | Institution-dominated | Retail-dominated |
Price Limits: No Individual Stock Limits vs Daily Price Caps
US Stocks: No Daily Price Limits
The first major characteristic of US stock movements is no individual stock price limits. A stock can rise by hundreds of percent or drop over 50% in a single day—and this is not uncommon in US markets. In April 2026, the SEC eliminated intraday trading restrictions and the $25,000 minimum equity requirement for pattern day traders, further lowering the barrier to day trading and theoretically allowing even greater price freedom.
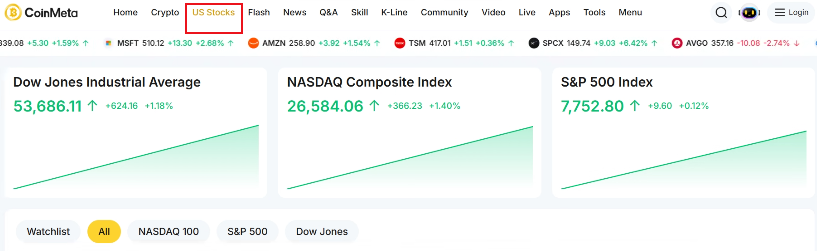
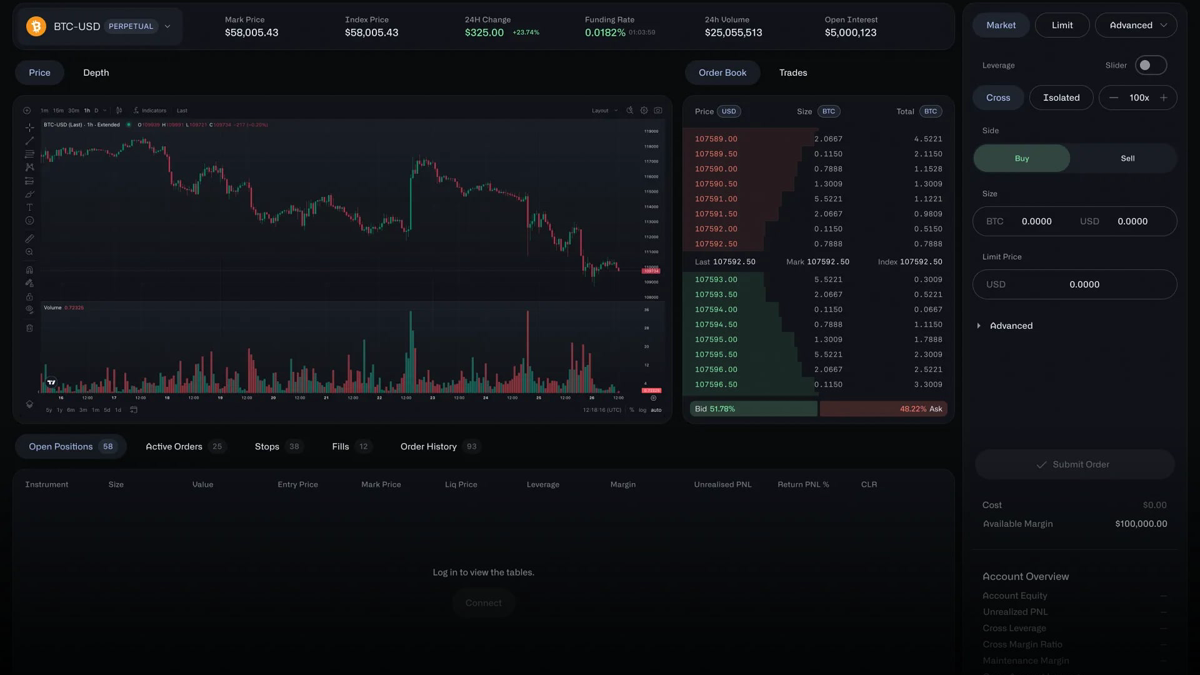
Coinmeta US Stocks Section
A-Shares: Strict Daily Price Caps
In contrast, A-shares operate under strict daily price limits: ±10% for the main board, and ±20% for the STAR Market and ChiNext. Effective July 6, 2026, the daily limit for ST and *ST stocks on the main board was also standardized from 5% to 10%. While these caps limit single-day volatility, they also create a situation where investors may be trapped in "limit-down" positions with no ability to sell during extreme market conditions.
Our take: No price limits allow US markets to achieve more efficient price discovery. A-shares' daily caps, while protecting retail investors, delay price adjustments and often lead to prolonged, grinding declines—a "slow bleed" effect.
Circuit Breakers: Index-Level vs Stock-Level Safeguards
While US stocks have no individual price limits, they are equipped with index-based circuit breakers that act as a market-wide "safety valve." Based on the S&P 500 index, there are three thresholds:
Level 1 (7% decline): Trading halts for 15 minutes
Level 2 (13% decline): Trading halts for another 15 minutes
Level 3 (20% decline): Trading halts for the remainder of the day
This mechanism was designed after the 1987 "Black Monday" crash, intended to provide a cooling-off period during extreme volatility.
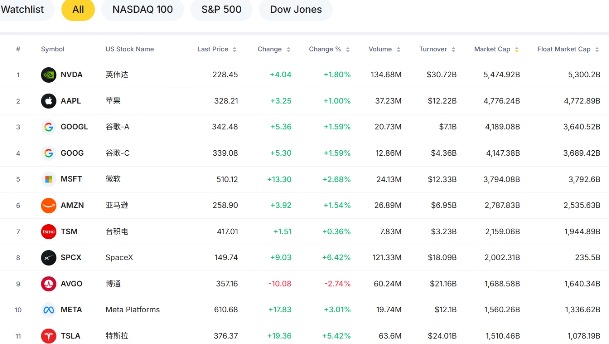
US Major Indices: Latest Price Moves
A-shares, on the other hand, apply circuit breakers at the individual stock level, not the broader market. When a stock hits its limit-up or limit-down, that specific stock stops trading, but the broader index and other stocks continue to trade as usual.
The distinction: US circuit breakers guard against systemic risk, while A-share price caps aim to curb excessive speculation in individual stocks. These are fundamentally different approaches.
Trading Rules: T+0 Flexibility vs T+1 Overnight Risk
US Stocks: T+0 Trading
The third major characteristic of US stocks is T+0 settlement—shares bought during the day can be sold the same day, with unlimited intraday round-trips. Following the SEC's removal of PDT rules in April 2026, the barrier to retail high-frequency trading has further dropped. Combined with no price limits, single-day swings of over 50% have become common in US markets.
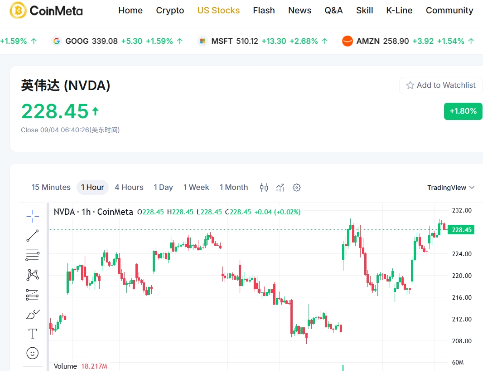
US Stocks: T+0 Settlement
A-Shares: T+1 Settlement
A-shares operate on a T+1 settlement basis—shares purchased today can only be sold the next trading day. This system was originally designed to curb excessive speculation and reduce market volatility, but it also means investors cannot correct their trading mistakes on the same day.
Our take: T+0 allows US markets to adjust prices more quickly and fully. T+1 forces A-share investors to bear overnight risk during volatile market swings. With the SEC's 2026 deregulation of retail day trading, the US market's liquidity advantage has further widened.
Short-Selling: Two-Way Pricing vs Restricted Bearish Bets
US Stocks: Mature Short-Selling Ecosystem
The fourth major characteristic of US stocks is a highly mature short-selling mechanism. Nearly all stocks can be shorted, with a 92% success rate for borrowing shares among S&P 500 constituents. A rich toolkit—including margin lending, options, futures, and other instruments—supports a comprehensive two-way price discovery mechanism.
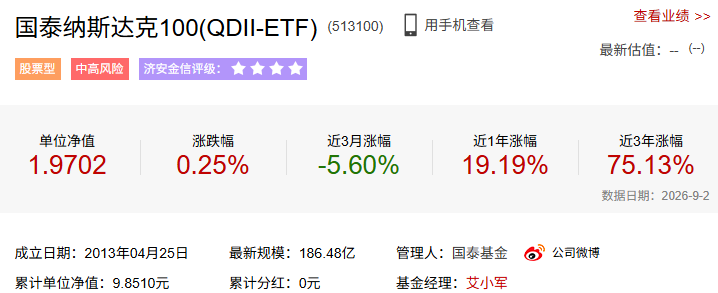
Examples of US Short-Selling Tools
A-Shares: Limited Short-Selling
A-share short-selling relies primarily on margin trading and securities lending, but available targets are limited, securities supplies are tight, and shorting costs are high. The market as a whole remains predominantly one-way (long-only). This structure leaves A-shares prone to periodic overheating, often followed by sharp cliff-like declines once market peaks are formed.
The bottom line: The US short-selling mechanism allows both good and bad news to be priced in quickly, with price movements more fully reflecting fundamental changes. A-shares, lacking effective short-selling constraints, tend to "overshoot" on the way up and "overshoot" on the way down.
Investor Structure: Institutional Dominance vs Retail-Driven Pricing
US Stocks: Institution-Dominated Market
The fifth major characteristic of US stocks is institutional dominance. Algorithmic and quantitative trading accounts for 60% to 73% of total US trading volume, while retail investor participation is only about 20% to 25%.
Specifically, the US market is shaped by the three index giants—BlackRock, Vanguard, and State Street—alongside mutual fund leaders like Fidelity and Capital Group, top hedge funds such as Citadel and Bridgewater, and mega-pension funds like CalPERS. These institutions collectively exert a profound influence on US market pricing and trends.
Institution‑led pricing places greater emphasis on fundamental analysis, resulting in a market characterized by "slow bull, sharp bear, and long-term upward" trends.
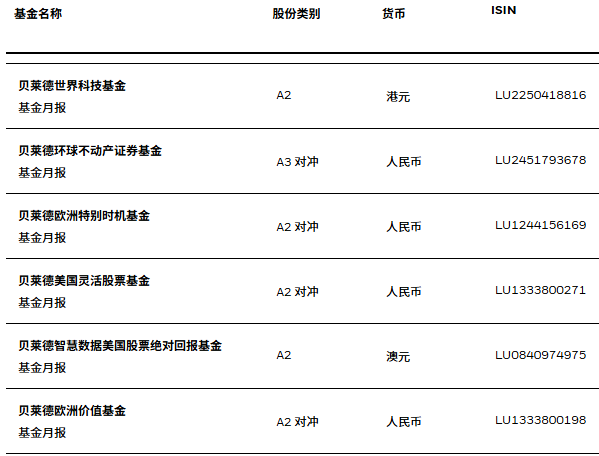
Major US Market Players – BlackRock Equity Funds
A-Shares: Retail-Dominated Market
A-share markets have long seen over 80% of trading volume coming from individual investors—a classic "retail market." Emotional trading runs high, with retail investors prone to chasing gains and panic-selling losses. The market is marked by "short bulls, long bears, sharp rallies, and steep sell-offs." Since 2010, US annual returns have generally stayed within ±30%, while A-share annual swings can reach as wide as ±50%.
Our take: Institutionally dominated US markets price more rationally, with prices tracking underlying values. Retail‑driven A-shares are more emotionally volatile, with prices often deviating from value. Understanding this dynamic is key to grasping why the same strategy can yield very different outcomes in these two markets.
Frequently Asked Questions
Q1: Since US stocks have no price limits, are they much riskier than A-shares?
A: Not necessarily. The lack of price limits simply allows prices to adjust fully within a single day, which actually improves pricing efficiency and avoids the "limit-down trap" common in A-shares, where investors cannot exit. The real risk lies not in the presence or absence of limits, but in the underlying fundamentals of the stock. Following the SEC's 2026 rule changes, day trading has become more active, but in an institution‑dominated market, the value anchoring effect remains strong—long‑term risk may not necessarily be higher than in A-shares.
Q2: Does T+0 trading really help retail investors better manage risk?
A: Yes, it does. The biggest advantage of T+0 is the ability to correct mistakes the same day. When unexpected bad news hits or a trading error occurs, investors can exit immediately, avoiding the overnight gap risk that A-share investors must bear. However, it also encourages higher trading frequency and impulsive decisions—after the 2026 retail rule changes, some investors actually saw higher intraday loss rates. The system itself is a double‑edged sword; discipline remains key.
Conclusion
The five core mechanisms of US stock movements—no price limits, index-based circuit breakers, T+0 trading, mature short-selling, and institutional dominance—together create a market where "prices clear quickly and information is priced efficiently." Meanwhile, A-shares' price caps, T+1 settlement, restricted short-selling, and retail dominance form a unique ecosystem where "risk is absorbed over time and volatility remains relatively contained."
Neither system is inherently superior or inferior. But investors must clearly recognize:
In US markets, you must learn to live with sharp volatility.
In A-share markets, you must learn to navigate time cycles.
Different mechanisms require different strategies. Understanding the rules of the game is the first and most essential step to success in either market.
Disclaimer: This content is based on publicly available market data and is for informational and educational purposes only. It does not constitute investment advice. Readers are advised to strictly comply with applicable laws and regulations. For the latest updates, follow Coinmeta.